Foreclosure Defense
Exposing Recent Mortgage Servicer Abuses: Junk Fees, Deceptive Notices, and Your Rights
Recent federal crackdowns and court rulings have exposed widespread mortgage servicer abuses, including illegal junk fees and deceptive foreclosure notices.
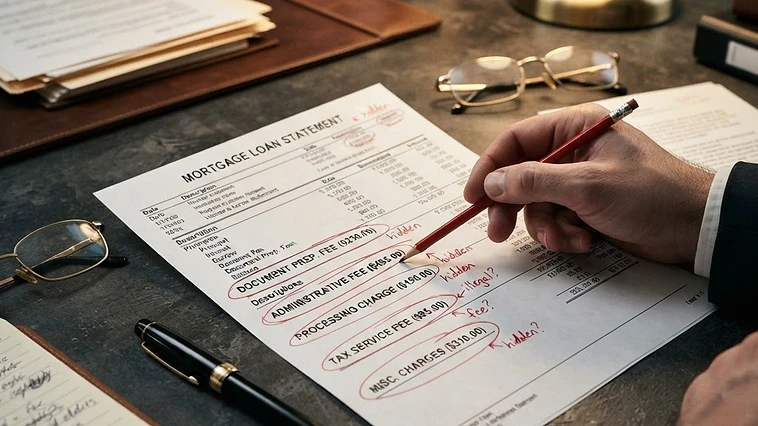
Disclaimer: The following article is for educational purposes only and does not constitute legal advice. If you are facing foreclosure, consult with a qualified attorney in your jurisdiction.
For homeowners struggling to keep up with monthly mortgage payments, the threat of foreclosure is a terrifying reality. But what happens when the very companies tasked with managing your loan—the mortgage servicers—engage in practices that actively push you closer to losing your home? Recent federal enforcement actions, regulatory reports, and appellate court rulings have pulled back the curtain on a disturbing trend of mortgage servicer abuses. From illegal "junk fees" to deceptive loss mitigation notices and violations of federal debt collection laws, the landscape of foreclosure defense is rapidly evolving.
Understanding these recent developments is critical for any homeowner currently behind on payments or actively fighting a foreclosure lawsuit. By learning how to scrutinize your mortgage statements, track loan assignments, and hold servicers accountable to federal standards, you can build a stronger defense. This article explores the latest findings from the Consumer Financial Protection Bureau (CFPB) and recent federal court rulings, breaking down exactly how these abuses occur and what they mean for your rights as a homeowner.
The Rise of Mortgage Servicer "Junk Fees" and Illegal Charges
One of the most significant recent developments in homeowner protection comes from the Consumer Financial Protection Bureau's latest Supervisory Highlights report, which placed a heavy focus on the residential mortgage servicing market. Federal examiners discovered a widespread pattern of servicers charging illegal and unnecessary fees—often referred to as "junk fees"—that artificially inflate a homeowner's debt and make it exponentially harder to catch up on missed payments.
When a homeowner falls behind on their mortgage, the servicer is authorized by the mortgage contract to charge certain fees, such as late fees or property inspection fees. However, these charges are strictly governed by the terms of the deed of trust, state law, and investor guidelines. The CFPB found that many servicers were blatantly ignoring these rules. For example, examiners detailed specific violations where servicers charged homeowners for property inspections that were explicitly prohibited by investor guidelines. In other cases, servicers assessed late fees that exceeded the maximum amounts allowed in the original mortgage agreements.
Furthermore, the federal report highlighted instances where servicers failed to waive existing fees following the acceptance of loan modifications, a direct violation of the terms offered to the homeowner. They also failed to provide adequate descriptions of these fees in periodic monthly statements, leaving homeowners entirely in the dark about why their balance was rapidly increasing. In some of the most egregious cases, servicers failed to make timely disbursements from escrow accounts for property taxes and insurance payments, causing the borrowers to incur heavy penalties through no fault of their own.
For a homeowner in foreclosure defense, these findings are a crucial piece of the puzzle. If a foreclosing plaintiff is claiming you owe a specific amount of money, but that amount is padded with illegal junk fees, unauthorized property inspections, and inflated late charges, the accuracy of their entire financial claim is called into question. Scrutinizing the payment history and demanding a full accounting of every fee assessed is a fundamental step in challenging the validity of the debt.
Deceptive Loss Mitigation Notices: What Homeowners Need to Know
Loss mitigation is the process where a homeowner and the mortgage servicer work together to find an alternative to foreclosure, such as a loan modification, forbearance, or repayment plan. Federal law, specifically Regulation X of the Real Estate Settlement Procedures Act (RESPA), imposes strict rules on how servicers must handle loss mitigation applications. Unfortunately, recent federal examinations have revealed that servicers frequently violate these rules, engaging in unfair, deceptive, and abusive acts or practices (UDAAP).
According to recent regulatory findings, mortgage servicers have been caught sending deceptive loss mitigation eligibility notices to consumers. In some instances, servicers sent notices to homeowners in default that contained false or misleading information about their options. Other servicers violated Regulation X by failing to provide a clear deadline for the homeowner to accept or reject a loss mitigation offer. Without a clear deadline, homeowners are left confused, and servicers may prematurely withdraw an offer and push forward with foreclosure proceedings.
 Magnifying glass examining mortgage servicer documents and foreclosure notices for illegal fees.

Additionally, federal regulators found that some servicers caused severe delays by failing to promptly submit completed loss mitigation applications to the loan investors for review. During these delays, homeowners continued to accrue interest and late fees, pushing them further into debt while they waited for an answer. The CFPB has recently proposed new rules to help streamline this process, aiming to reduce paperwork requirements and force servicers to focus on helping borrowers rather than rushing to foreclose. However, until these systemic issues are fully eradicated, homeowners must remain vigilant. Documenting every communication, keeping copies of all submitted applications, and tracking the servicer's response times are vital strategies for proving that a servicer failed to comply with federal loss mitigation requirements.
Federal Courts Rule Foreclosure is Debt Collection Under the FDCPA
Another major battleground in foreclosure defense involves the Fair Debt Collection Practices Act (FDCPA). The FDCPA is a federal law enacted to outlaw abusive, deceptive, and unfair debt collection practices. For years, mortgage servicers and their foreclosure attorneys have attempted to argue that they are merely enforcing a security interest (the mortgage lien) and are not actually "collecting a debt," thereby trying to shield themselves from FDCPA liability.
Recent federal appellate court rulings have struck down this defense. In the recent case of Palazzo v. Bayview Loan Servicing, LLC (4th Cir.), a homeowner in bankruptcy proceedings sued his mortgage servicers, alleging that the written communications they sent him were illegal attempts to collect a discharged debt in violation of the FDCPA. The mortgage servicers argued that their letters contained disclaimers stating they were not attempting to collect a debt, but rather just providing informational account statements and alternatives to foreclosure.
The appellate court rejected the servicers' arguments. The court held that despite the boilerplate disclaimers hidden in the fine print, the letters clearly listed the principal balance, the next payment due date, a payment coupon, and the total amount due. The court emphasized that enforcing a mortgage lien against a property is, by definition, a means of collecting a debt. Because foreclosure is a method of debt collection, the communications sent by the servicer were subject to the strict rules of the FDCPA.
This ruling is a powerful tool for homeowners. It means that mortgage servicers and their law firms cannot hide behind generic disclaimers when they send threatening letters, payoff statements, or monthly invoices. If a servicer uses false, deceptive, or misleading representations in connection with the collection of the mortgage debt, or if they attempt to collect amounts not expressly authorized by the agreement or permitted by law (such as the junk fees mentioned earlier), they may be liable for FDCPA violations. Homeowners can use these violations not only to seek damages but also to challenge the servicer's overall credibility and legal standing in the foreclosure action.
How Servicers Mishandle Loan Transfers and Assignments
Beyond fees and communications, the actual ownership and transfer of the mortgage loan remains a heavily contested issue in foreclosure defense. During the housing boom, millions of mortgages were bundled together and sold to Wall Street investors in a process known as securitization. This process required a strict chain of title, with the promissory note and the deed of trust (or mortgage) being properly endorsed and assigned from one entity to the next.
Recent court cases continue to highlight the sloppy, and sometimes fraudulent, ways that servicers handle these transfers. In cases like Sears v. Rocket Mortgage and various bankruptcy proceedings involving entities like Select Portfolio Servicing and U.S. Bank, homeowners have challenged the validity of the loan assignments. Often, a homeowner will discover that the foreclosing trust claims to own the loan, but the public land records show a completely different chain of title, or the assignment was executed years after the securitized trust officially closed.
While courts have sometimes ruled that borrowers lack standing to challenge the internal pooling and servicing agreements of these trusts, homeowners absolutely have the right to demand that the foreclosing party prove they are the true holder of the note and have the legal standing to foreclose. If the documents show that the loan was never actually transferred into the trust, or if the assignment was "robo-signed" by an individual who lacked the authority to execute the document, the foreclosing entity's case can be severely undermined. Organizing your evidence, requesting a complete collateral file through discovery, and meticulously tracing the history of your loan's assignments are essential steps in exposing these fatal flaws in the bank's case.
Why the Foreclosure Defense Survival Playbook Helps
Navigating the treacherous waters of mortgage servicer abuses, illegal junk fees, deceptive loss mitigation tactics, and complex legal doctrines like standing and FDCPA violations is nearly impossible without the right knowledge. The banks and their servicers rely on the fact that most homeowners do not understand how to read a mortgage statement forensically, how to spot a fabricated assignment, or how to hold them accountable for federal regulatory violations.
This is exactly why the "Foreclosure Defense Survival Playbook" is an indispensable resource for any homeowner fighting to save their property. This comprehensive 530-page educational guide breaks down the complex world of foreclosure procedures into plain, understandable language. It teaches you step-by-step how to organize your evidence, how to audit your mortgage statements to uncover hidden junk fees, and how to conduct the legal research necessary to understand your rights under laws like RESPA and the FDCPA.
Whether you are just starting to fall behind on payments or you are already deep into a pro se litigation battle, the Playbook provides the foundational education you need to level the playing field against aggressive mortgage servicers. Don't let deceptive notices and illegal fees cost you your home. Equip yourself with the knowledge to fight back—order the Foreclosure Defense Survival Playbook today and take control of your defense.


Order The Playbook
Get the Foreclosure Defense Survival Playbook
530 pages of structured, educational guidance covering mortgage documents, foreclosure procedures, evidence organization, and legal research — the same foundation this article draws from.